According to the National Highway Traffic Safety Administration (NHTSA), an estimated 36,640 people died in motor vehicle traffic crashes in the United States in 2025. The decline was already evident during the first half of the year, when NHTSA estimated that 17,140 people died in traffic crashes, 8.2% fewer than during the same period in 2024.
The average bodily injury liability claim was $28,278 in 2024, the latest full-year figure available in Triple-I’s 2025 data, and the average property damage liability claim was $6,770.
The amount a person ultimately receives can be significantly higher or lower depending on the circumstances of the accident. But what is the average settlement for a car accident? Let’s take a closer look.
Why “Average” Is a Misleading Word Here
Outliers drag averages into completely opposing directions. A few injury settlements amounting to millions of dollars find themselves in the very same set as thousands of small car accident settlements amounting to hundreds of dollars each, and mixing the two into an average results in a number that is simply not representative of people’s experience.
Self-report surveys of claimant outcomes, industry claims data, and law firm outcome data all yield their own averages, primarily because they measure different things.
A survey taking into account every single claim, especially those involving unrepresented drivers that settled for a small amount right away, is likely to show a lower number than a set of law firm data.
What Actually Moves the Number for a Specific Case
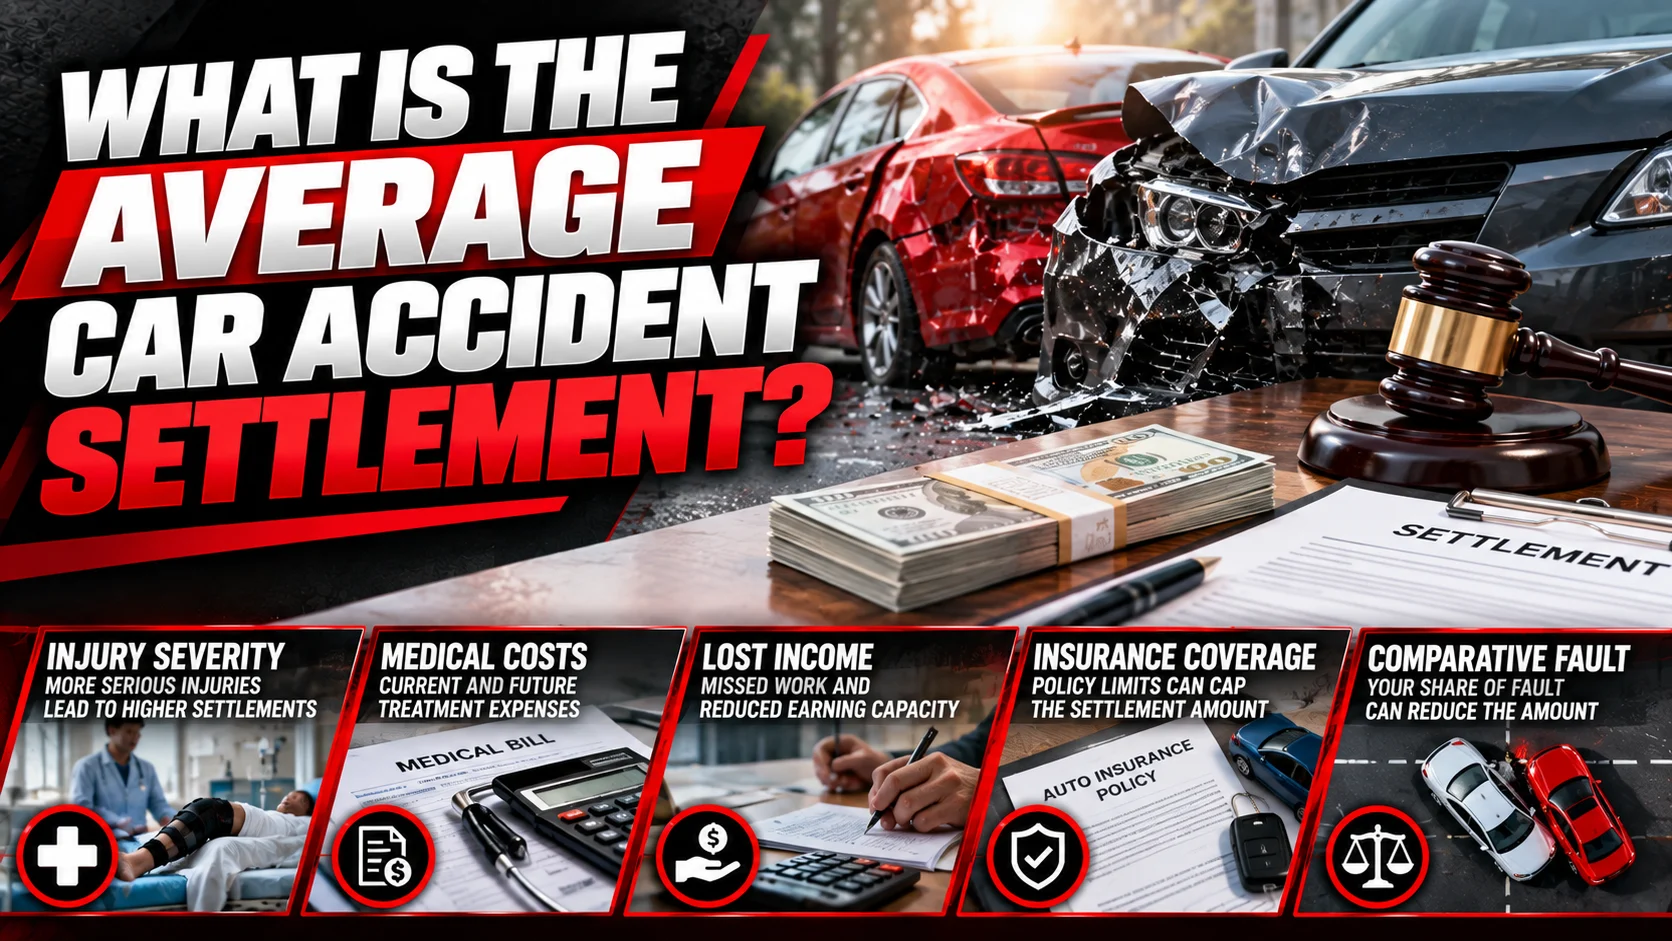
There is nothing that impacts settlement values more than the severity of the injury. A case of whiplash that takes a matter of weeks to settle will end up being worth much less than a case of a spinal cord injury or brain injury, and there can be an enormous difference in dollars.
Documented medical costs, both what’s already been spent and what future treatment will realistically cost, tend to anchor the economic side of a claim. Lost income matters too, particularly when an injury keeps someone out of work for an extended period or permanently limits what kind of work they can do going forward.
Insurance policy limits cap the picture on the other end. It often set a practical ceiling, since recovery beyond the at-fault driver’s coverage usually depends on that driver’s personal assets or other policies.
Comparative Fault Can Reduce a Settlement Even in a Strong Case
Most states use some form of comparative negligence, where the share of liability of a claimant will reduce their total award by that percentage. Some states do not allow the recovery in cases where a claimant reaches a certain threshold of being at fault.
This is significant since the claims adjusters routinely look for any basis to assign part of the fault to the claimant, since every percentage point reduces the payout.
A very solid case may end up receiving a much smaller settlement than was anticipated if an adjuster can show that the claimant was at all at fault.
Representation Changes the Outcome More Than People Assume
The reason why the claimant that hires an attorney gets compensated better is because, in addition to negotiating leverage, the claimant that negotiates alone doesn’t ask for all the compensation to which he is entitled since he doesn’t know the true value of his claim.
Another reason why hiring an attorney helps to get compensated better is because of the thoroughness of the attorney that knows all the aspects of the claim that need to be considered.
In Connecticut, the help of a Wallingford car accident lawyer can assist in working negotiations without requiring any upfront payment. The fee comes out of whatever the case ultimately recovers, which removes the cost barrier that keeps some injured drivers from seeking representation in the first place.
The Practical Reality
You should not mistake the national average as a prediction for any specific case. This could lead to disappointment on one end or an unrealistic expectation on the other.
The number that matters is built from different factors. The case itself, the injuries and medical costs, and the available insurance coverage. You also need to consider the state’s fault rules, not from a blended industry figure that was never meant to describe an individual claim in the first place.