
Tire financing & payment guide
Replacing worn tires can be expensive, especially when you need four at once. The Discount Tire credit card, issued by Synchrony Bank, lets approved shoppers finance qualifying tire and wheel purchases. But understanding the terms matters just as much as knowing your monthly payment.
Financing offersInterest & feesSynchrony paymentsFAQs
This guide explains how the card works, promotional financing, potential charges, payment methods, and what to review before applying.
Quick answer
Discount Tire offers a Synchrony-issued credit card with promotional deferred-interest financing on qualifying purchases. You can avoid promotional interest by paying the entire qualifying balance before the offer expires. Always check the specific terms shown at checkout.
01 / Understand the card
What Is the Discount Tire Credit Card?
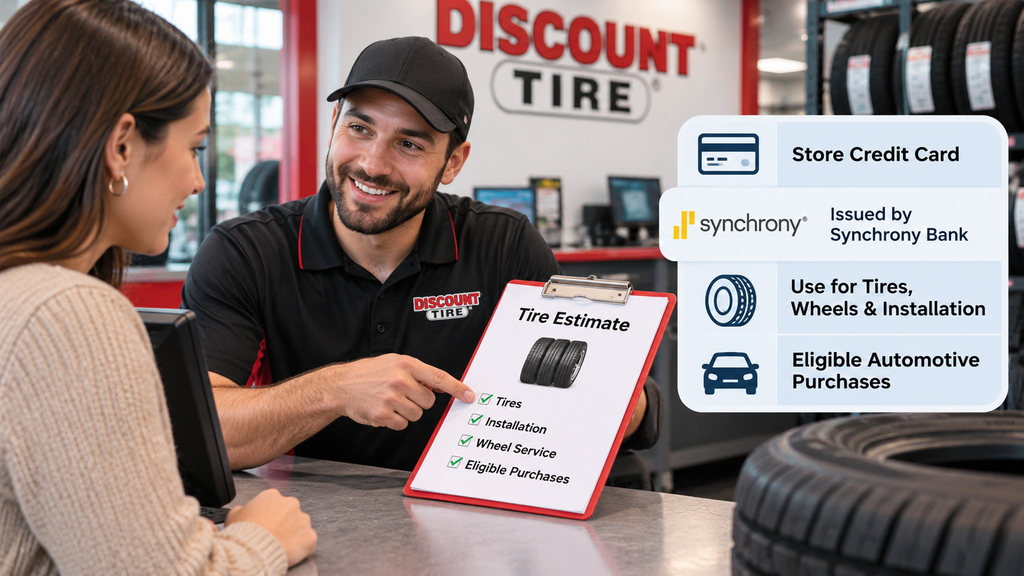
The Discount Tire card is a store-branded credit card issued by Synchrony Bank. Approved customers can use it for eligible tire, wheel, installation, and other participating automotive purchases instead of paying the entire amount upfront.
$0
Published annual fee
Synchrony
Card issuer
6–12 mo.
Advertised promotional terms*
*The promotional period depends on the purchase amount and the offer available at the time of purchase. Credit approval required.
Where Can You Use the Card?
It can be used at participating merchants in the Synchrony Car Care network, including eligible Discount Tire purchases. Certain automotive repair, maintenance, and fuel purchases may also qualify for regular card use. Do not assume every purchase qualifies for promotional financing. Confirm acceptance and the offer before paying.
02 / Compare payment plans
How Does Discount Tire Financing Work?
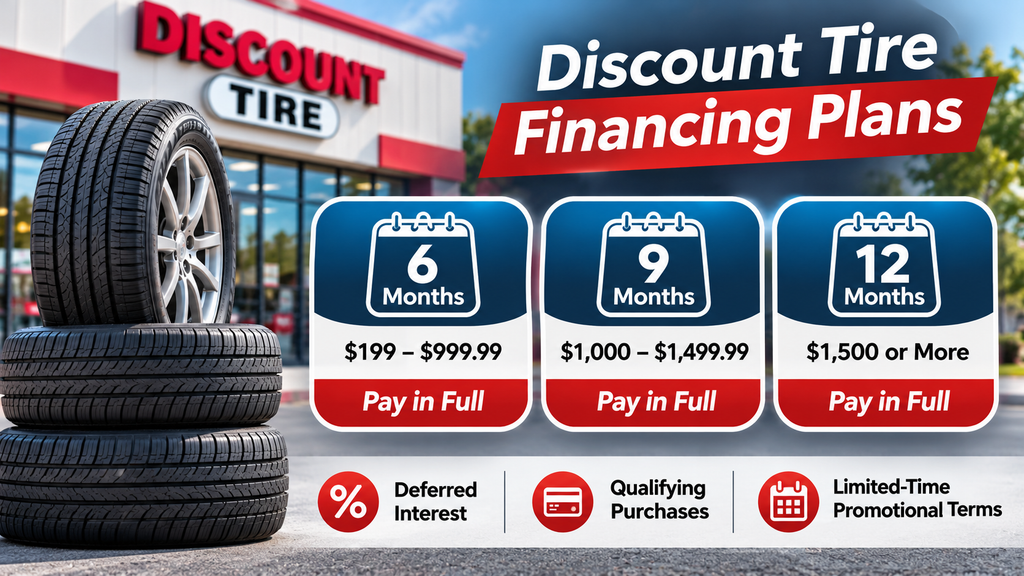
Qualifying purchases may receive one of the advertised deferred-interest financing periods below. These are examples of published offer tiers, not guaranteed terms for every transaction.
| Qualifying purchase | Period | Main condition |
|---|---|---|
| $199–$999.99 | 6 months | Pay in full |
| $1,000–$1,499.99 | 9 months | Pay in full |
| $1,500 or more | 12 months | Pay in full |
Qualifying purchase thresholds, eligible transactions, and promotions can change. Consult the current Discount Tire offer disclosures.
What Does “No Interest if Paid in Full” Mean?
It generally means deferred interest: interest accrues during the promotion but is waived if you pay the entire promotional balance before the deadline. This is different from an offer that charges 0% APR throughout the promotional period.
Important: Minimum payments may not be enough. If any promotional balance remains at expiration, accrued interest may be charged retroactively from the purchase date under the offer’s terms. Plan around the expiration date—not just the minimum payment on your statement.
Example: A $1,200 Tire Purchase
Suppose a qualifying $1,200 purchase receives a nine-month promotion. The following amounts illustrate how to plan to finish paying before the deadline.
| Budget item | Amount |
|---|---|
| Purchase amount | $1,200 |
| Promotional period | 9 months |
| Illustrative monthly payment | $133.34 |
| Nine payments total | $1,200.06 |
This hypothetical example assumes no other balance, additional charges, or payment-allocation issues. It is not Synchrony’s required minimum payment. Check the exact deadline and consider paying earlier.
03 / Know the real costs
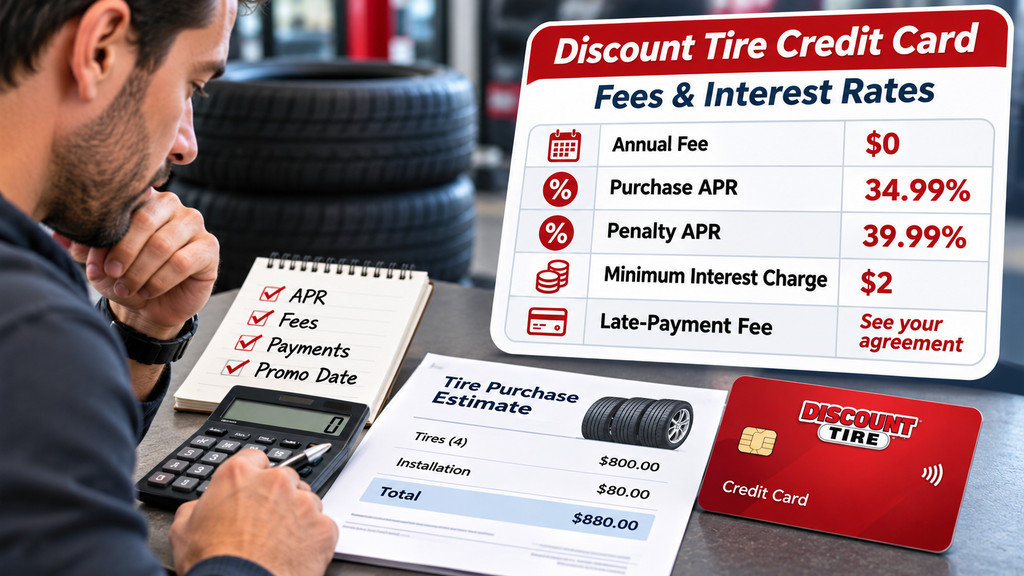
Discount Tire Credit Card Fees and Interest Rates
Read the card agreement before applying. The following figures appeared in published new-account terms dated July 31, 2025; they should not be assumed to apply to every existing account or offer.
| Rate or fee | Published figure |
|---|---|
| Annual fee | $0 |
| Purchase APR | 34.99% |
| Penalty APR | 39.99% |
| Minimum interest charge | $2 |
| Late-payment fee | See your current agreement |
Rates, penalties, and other terms can differ by account and may change. Always use your own card agreement and latest statement to verify the applicable charges.
Can Promotional Financing Become Expensive?
Yes. Not clearing the promotional balance on time can trigger previously accrued interest. Missing payments can also lead to late fees and other account consequences. Set reminders and aim to pay off the promotional balance before its expiration date.
04 / Make a payment
How to Make a Discount Tire Credit Card Payment
Synchrony manages the card’s account services. The simplest way to make a Discount Tire credit card payment is through the official account portal.
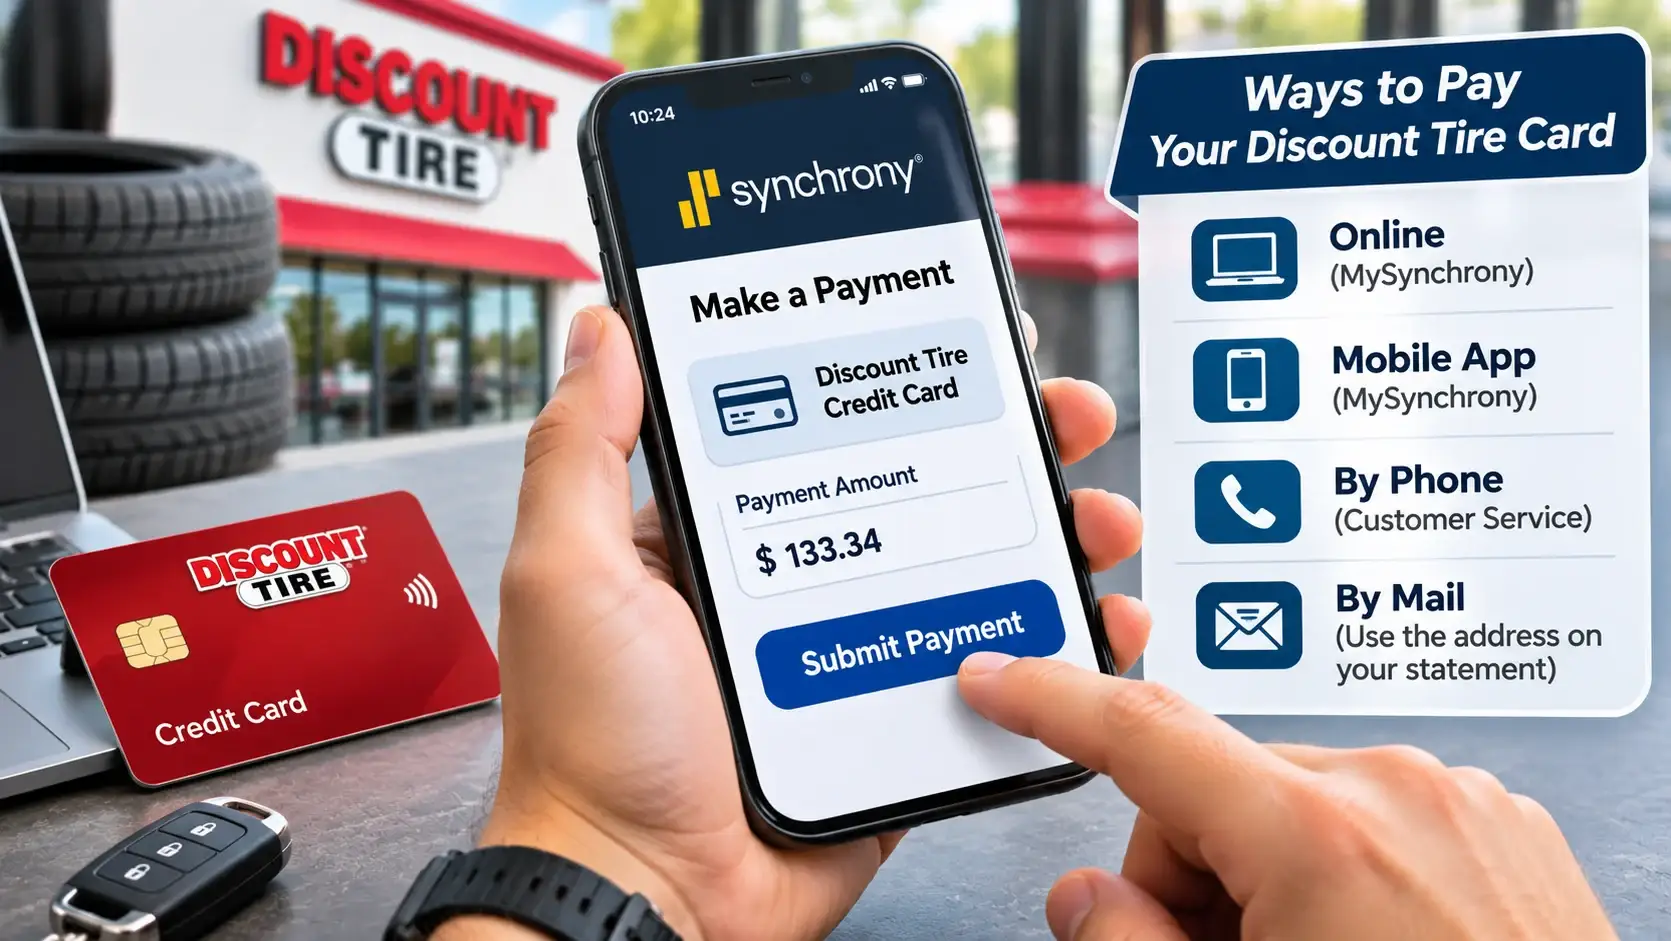
Pay Online Through Synchrony
- Go directly to the officialMySynchrony website.
- Sign in, or register your card account if this is your first visit.
- Open the payment section and choose the amount to pay.
- Select the payment date and review the information.
- Submit the payment and keep the confirmation for your records.
Other Ways to Pay
Depending on your account, you may be able to pay using the MySynchrony app, by phone, or by mail. Use the contact number and remittance address on your statement, and allow extra processing time for mailed payments.
Payment tip
Automatic minimum payments can help prevent missed due dates, but they might not pay off a promotional purchase before deferred interest becomes due.
05 / Decide confidently
How to Apply and Is the Card Worth It?
Start with the official Discount Tire website and follow its current credit card offer to review eligibility, promotions, and terms. An advertised prequalification check may not affect your credit score; submitting a formal application may affect it. Approval and credit limits are determined by the issuer.
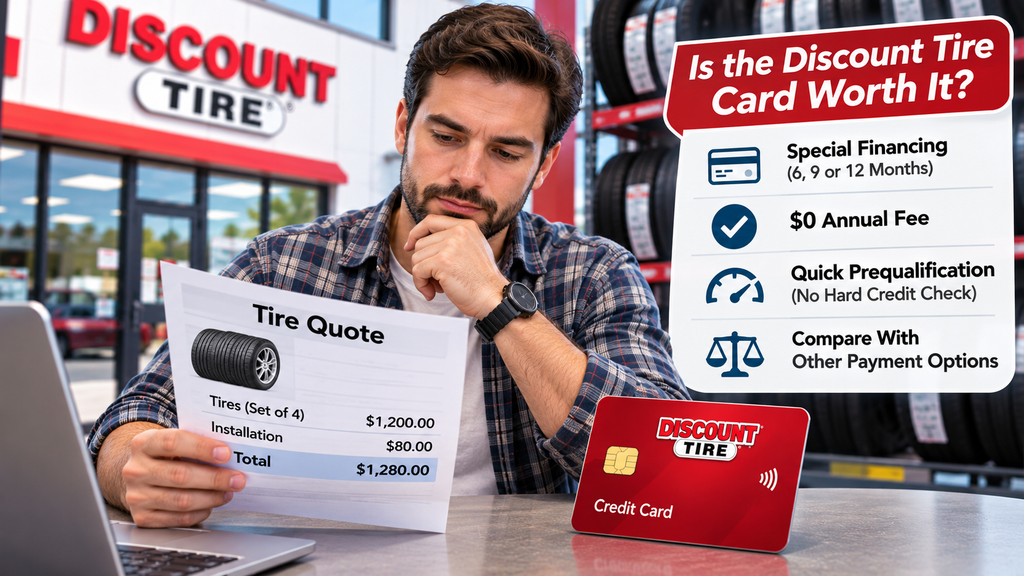
Before You Apply: Four Quick Checks
- Confirm the current financing offer and purchase threshold.
- Check the promotional expiration date and the APR.
- Make a realistic payment plan that clears the balance early.
- Compare paying upfront or other available financing options.
Financing may be useful if you need tires now and can comfortably repay the balance. Paying upfront removes the risk of deferred-interest charges. Discount Tire may also offer separate financing options, such as Affirm, with their own terms.
Answers to common questions
Frequently Asked Questions
Is Synchrony Bank the Discount Tire card issuer?
Yes. Synchrony Bank issues the card and manages its billing, payments, and account services.
Can I use the card at gas stations?
The card may be accepted at participating Synchrony Car Care merchants, including eligible fuel merchants. Gas purchases are not automatically eligible for Discount Tire promotional financing.
Does checking prequalification hurt my credit score?
When the offer specifically states that prequalification uses a soft inquiry, that check does not affect your score. A full credit application may involve a hard inquiry and can affect your score.
Does the card have an annual fee?
Published Discount Tire card terms list no annual fee. Verify the agreement provided for your application.
What happens if I miss a payment?
A missed payment may lead to late fees, other interest consequences, and potential credit-reporting effects. Contact Synchrony promptly if you are having difficulty making a payment.
Are Discount Tire and Tire Discounters credit cards the same?
No. They are different retailers with distinct credit programs. Discount Tire’s card is issued by Synchrony Bank; Tire Discounters has offered a card issued by Citibank. Check each retailer’s current terms independently.
Final Thoughts
The Discount Tire card can spread the cost of essential tire purchases, but the biggest factor is your repayment plan. Compare options, verify the current terms, and choose a payment amount that will clear any promotional balance before the deadline.
Bottom line: A financing offer is only helpful when the total cost and repayment schedule work for your budget.